Yes, the ATO can class a WA holiday home as a “leisure facility”, and that label takes most of your deduction claims with it. It happens when the ATO decides the property is mainly there for your own enjoyment rather than to earn rent. The test sits in TR 2026/1, which the Commissioner issued on 20 May 2026. The transitional grace period ended on 30 June 2026, so anything you spend from 1 July 2026 onwards is in scope. Owners in Mandurah, Busselton and Margaret River who keep the peak weeks for themselves are the clearest cases.
What the ATO Actually Means by “Leisure Facility”
A leisure facility, in ATO terms, is land or a building used, or held for use, for holidays or recreation. A holiday home is simply one type of leisure facility, which is why section 26-50 of the Income Tax Assessment Act 1997 catches it. The ATO looks past your rental listing and checks how the property is actually used across the year.
This matters because a standard rental property lets you claim costs like interest, rates, insurance and repairs, apportioned for any private use. A holiday home caught by section 26-50 does not get that treatment at all. The denial is closer to all or nothing: if the property fails the test, every loss and outgoing relating to owning or using it is denied for the whole income year, rather than being scaled back for the weeks you were there.
One exception cuts the other way. Costs that relate only to renting the place out, such as platform commission, advertising and cleaning between guests, stay fully deductible even when section 26-50 applies. It is the ownership costs that disappear.
O’Brien Accountants & Advisors have a longer write-up on how the ATO separates genuine rental intent from private enjoyment. It was written against the November 2025 draft guidance, not the final ruling, so watch the dates as you read it.
Where TR 2026/1 Fits In
TR 2026/1, titled Income tax: rental property income and deductions for individuals who are not in business, is the ruling that formalises this leisure facility test. The Commissioner issued it on 20 May 2026. It replaces the old IT 2167, which was withdrawn on 12 November 2025, the day the draft version (TR 2025/D1) went out for public comment.
The two dates get mixed up constantly. November 2025 is when the draft appeared, not when the rules started. The final ruling applies to income years commencing both before and after its issue date, but Appendix 2 sets out a transitional compliance approach: the ATO will not review whether section 26-50 applies to expenses incurred before 1 July 2026. That window has now closed. Expenses from 1 July 2026 onwards are the first that will actually be tested.
Two Practical Compliance Guidelines sit alongside the ruling. PCG 2026/3 sets out the green, amber and red risk zones the ATO uses to work out whether your holiday home is mainly held to earn rent. PCG 2026/2 covers fair and reasonable apportionment for the cases where section 26-50 does not apply. What the ATO weighs in a holiday home case is your occupancy pattern, the price you asked, and whether the advertising was ever a real attempt to fill the calendar. Owners had considerably more room under IT 2167.
Why WA Coastal Owners Are Squarely in the ATO’s Sights
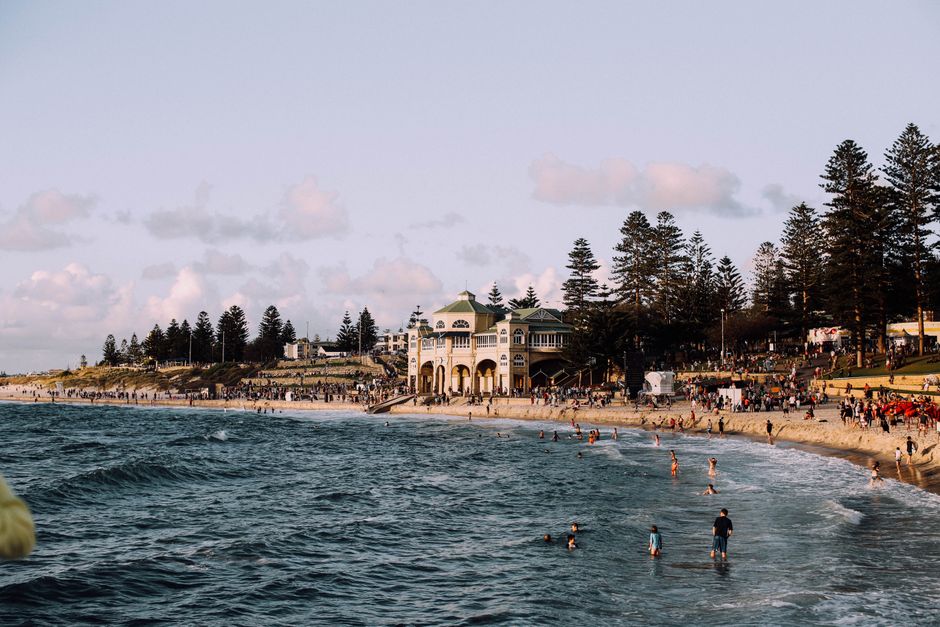
Mandurah, Margaret River and Busselton are classic dual-use holiday home locations. Owners buy near the coast partly to enjoy it themselves, and partly to earn rental income when they are not there. That mix is exactly what draws ATO attention.
Peak season personal use is the biggest red flag. If you block out your Busselton property over Christmas or use your Mandurah unit during the summer school holidays, the ATO notices. These are the weeks with the highest guest demand and the highest nightly rates, so blocking them out looks like you are prioritising your own enjoyment over rental income.
Amarose make the same point in their rundown of the 2026 holiday home tax rules: coastal and tourist-zone properties have obvious seasonal demand, which makes an owner’s own use easy to spot against it. That is most of why those postcodes get looked at first.
The ATO’s Own Worked Examples, Explained
TR 2026/1 runs through several holiday home examples. None of them are set in WA, but the pattern is exactly what plays out in Busselton, Margaret River and Mandurah every summer.
The example that fails is Example 13. Daniel and Kate own a house near the beach in an area popular with summer holidaymakers, advertise it through sharing platforms, and block out the school holidays for their own use. They take two weeks over Christmas and New Year every year, plus another two to three weeks across the rest of the year. Because their own use keeps landing on peak rental periods, they end up renting the house out for only around 10 to 14 days annually. The ATO’s conclusion is that the house is a holiday home not mainly used to produce rental income, so every loss and outgoing relating to ownership is denied. They can still claim 100% of the platform’s service fees and commission.
Example 12 fails harder. Carla lives in Sydney and owns a beach house in the Whitsundays, advertised year round through an agent, but blocked out for the family over Easter, Christmas and New Year and the school holidays, whether or not the family actually turns up. She rejects most applicants and has cancelled bookings so she could use the house herself. It rents out for an average of five days a year.
The example that passes is Example 11, and it is the one most owners should be aiming at. Eve owns a property in a seaside location and earns most of her income during the peak summer season. During off-peak periods, when there are no bookings, she occasionally uses the property for one or two nights a year. She never reserves it for her own use. Her deductions survive, and she simply apportions them for the nights she stayed.
Read those three together and the test comes into focus. One off-peak night does not sink you. A standing pattern of reserving the peak weeks, combined with very little actual renting, does.
Turning the Examples Into Your Own Self-Test
You can run the same logic on your own property. Start by listing every date you personally used your holiday home last year. Then check which of those dates fall during high-demand periods for your area.
For a Mandurah or Busselton owner, that means Christmas, Easter, and the WA school holiday blocks. For Margaret River, add the wine and food festival season, which draws strong tourist demand.
Next, ask one question of each personal-use date: could I have rented this night at a premium rate? If the honest answer is yes, that night counts against you, and the more of them you have, the closer you sit to the leisure facility category.
Then count the nights you actually rented, because both numbers matter. The ATO is explicit that a time-based calculation is not enough on its own. But the time a property spends dedicated to earning income is one of the things it weighs, and in Example 13 the tiny rental count is what tipped the outcome.
The Peak Period Trap: Christmas, Easter and School Holidays
Peak periods are where most WA holiday home owners get caught out. It is tempting to keep a week over Christmas for family, or grab the Easter long weekend before guests book it. But these are exactly the weeks the ATO scrutinises most closely.
Even a short personal stay during a high-demand window moves you out of the ATO’s green zone. Under PCG 2026/3, using the property, or holding it available for yourself, during school holidays, public holidays or peak seasonal demand periods is an amber zone factor. Making a habit of blocking out those dates each year is a red zone factor. You do not have to spend months there for it to register.
School holidays are a particular trap in WA. There are four periods a year, and coastal towns like Busselton and Margaret River see strong demand in every one. Blocking out even part of one period, especially in summer, adds to your risk profile.
Bentleys’ short-term rental tax guide lists the availability criteria the ATO expects owners to meet, if you want a second source on where the line sits.
Self-Assessment Checklist: Is Your Property at Risk?
Run through this checklist honestly before you lock in your calendar for the coming peak season. It mirrors the risk factors the ATO sets out in PCG 2026/3. The year being tested is the one you are living in right now, not the one you are about to lodge for.
- Nights you personally used the property in the last 12 months, plus any nights you held it available for yourself without renting it
- Total nights the property was actually rented, and how that compares with the nights it was advertised
- Whether any of your personal nights fell in peak periods (Christmas, Easter, school holidays, public holidays, local festivals)
- Whether your listed price matched market rates for that time of year, not an inflated “no one will book this anyway” price
- Whether you knocked back or cancelled bookings, or set minimum stays that made peak weeks hard to book
- Gaps in your booking records, calendar exports, or income statements
- Any pattern of blocking dates just before or after a personal stay, which can look like disguised personal use
If you tick several risk boxes, especially around peak-period blocking, you may be heading towards a leisure facility classification.
How This Interacts With WA’s 90-Night STRA Rule
WA’s short-term rental rules and the ATO’s tax rules are separate systems, but they both hinge on the same thing: accurate records of how your property is used.
The 90-night figure gets misread in two ways. It is not a legal cap on how many nights you can let. It is the threshold below which unhosted short-term rental accommodation is exempt from needing development approval. Go past 90 nights (non-consecutive) in a 12-month period and you need planning approval from your local council.
It also does not apply everywhere. Under the WA planning reforms, that exemption covers the Perth metropolitan area only. Mandurah sits in the Peel region, and Busselton and Margaret River are well outside the metro boundary, so for those properties it is up to the local government whether development approval is needed at all, potentially from the first night. Registration on the state STRA Register has been mandatory statewide since 1 January 2025 either way.
Tax deductibility is a different question entirely, but the record-keeping overlaps heavily. If you are already tracking nights for STRA compliance, you are halfway to building the evidence the ATO wants too. Read our guide to Perth’s 90-night STRA cap if you have not mapped out how the rule affects your property yet.
Personal Use vs Rental Use: Getting the Balance Right
Most WA owners want some personal use of their holiday home, which is fair enough. It just needs structuring. Two habits do most of the work: keep your own stays out of the peak windows, and record every date the property was rented, available, or used by you.
If personal use is a small, occasional thing outside peak periods, you are on safer ground. If it regularly eats into your highest-earning weeks, it may be time to consider shifting towards a fully rented model. Our guide on short-term versus long-term rental strategy can help you weigh up what that shift looks like financially.
For more detail on where the deduction boundaries sit, the ATO’s PCG 2026/3 works through eleven examples across the three risk zones. The Spectrum Financial Advisors guide covers what Busselton and Mandurah owners need to declare on their Airbnb income, though it was written against the draft rulings rather than the final versions.
Apartment and Strata Owners: What Changes
If your holiday home is a unit or apartment, strata by-laws come into it as well. Some schemes restrict short-term letting outright, and separately, every STRA property in WA has to sit on the state register regardless of what the by-laws say.
That feeds into the leisure facility test, though not in the way most owners assume. A limit imposed on you from outside does not count against you by itself. In PCG 2026/3 Example 4, a council rule capping the owners at 180 rental days a year still lands them in the green zone, because within the days they did have, they never blocked out peak demand for themselves and actively worked the calendar to maximise income. What the ATO weighs is how you use the availability you have, not how much of it the rules leave you. Keep the by-law or council correspondence on file so you can show why availability was restricted. Our article on strata by-laws versus WA STRA registration explains how these overlapping rules affect unit owners specifically.
This article is general information based on TR 2026/1 and PCG 2026/3, not tax advice. Your own circumstances decide the outcome, so talk to your accountant or a registered tax agent before you act on any of it.
Let Sepal Stays Help You Stay on the Right Side of the ATO
Staying out of the leisure facility category is mostly a records-and-calendar problem, and it is the part owners tend to let slide once the season gets busy.
When Sepal Stays manages your Mandurah, Busselton or Margaret River property, we keep the calendar genuinely open through peak periods, price it at what the market is actually paying, and keep the occupancy records that back that up. If the ATO ever asks, you have something to show them. Have a look at our Airbnb management services in Perth if that is the part you would rather hand over.
If you want to check where your property stands before you commit your calendar for Christmas and the summer holidays, get in touch through our contact form at Sepal Stays and we will walk you through your options.
Frequently Asked Questions
Does staying in my holiday home for a weekend affect my tax deductions?
It can, especially if that weekend falls in a peak period like summer or school holidays. Under PCG 2026/3, personal use during peak demand is an amber zone factor, and a regular pattern of blocking those dates each year is a red zone factor.
What is TR 2026/1 and when does it start applying?
TR 2026/1 is the ATO’s ruling on rental property income and deductions for individuals who are not in business, and it explains when a holiday home is treated as a “leisure facility” with ownership deductions denied. The Commissioner issued it on 20 May 2026. A transitional approach shielded expenses incurred before 1 July 2026, so expenses from that date onwards are the first that will be reviewed.
Can I still claim deductions if I list my property on Airbnb year round?
Year-round advertising on its own is not enough. In the ATO’s Example 12, the property was advertised year round through an agent and still failed, because peak dates were blocked and it rented for about five days a year. Genuine availability at market rates during high-demand periods is what counts.
How does the 90-night STRA rule relate to my tax deductions?
They are separate rules. The 90-night figure is a WA planning threshold: unhosted short-term rental in the Perth metropolitan area is exempt from development approval up to 90 nights in a 12-month period, and outside the metro area your local council decides. Tax deductibility is decided by the ATO under section 26-50. Both depend on accurate records of how many nights your property is rented versus personally used.
Is a Mandurah or Busselton holiday home more likely to be classed as a leisure facility than a Perth metro rental?
Coastal and holiday-destination properties with clear seasonal demand patterns are more likely to attract ATO attention because personal use during peak tourist periods is easier to identify.
Should I use a property manager to protect my deduction claims?
It helps, mainly because a manager keeps the calendar open in peak season and leaves a paper trail of what was listed, at what price, and who stayed. You can do all of that yourself. The usual failure is that the records go patchy in the months you were busiest.